In a recent speech at an event this week, Pierro Cipollone, Executive Board Member at the European Central Bank (ECB) revealed how the digital euro aims to complement the private sector, how it will not accrue interest, and how it aims to mitigate tokenised fragmentation.
The European Central Bank’s (ECB) central bank digital currency, the digital euro, intends not to compete against private banks and payment schemes, but to act as infrastructure for the digitisation of finance.
During a speech at MNI Connect this week, ECB Executive Board Member Piero Cipolline outlined what banks, payment service providers and merchants can expect from the digital euro before its planned 2029 issuance.
One of the primary concerns from private payment schemes and providers, particularly from the European Payments Initiative (EPI) and its development of Wero, is that the digital euro would negatively impact the private sector.
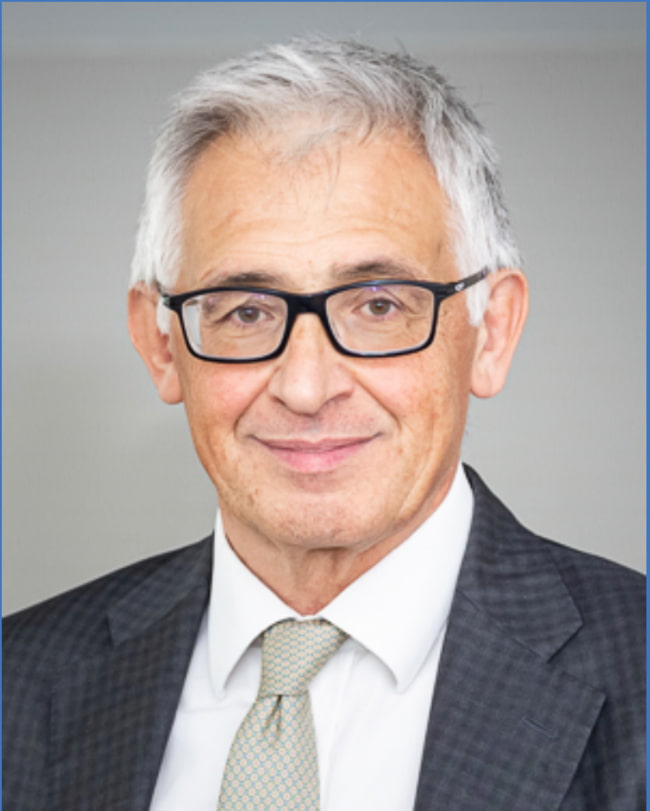
Cipollone stated that the CBDC would act as a risk-free alternative for when private payment methods are either down, or lacking the infrastructure to complete a transaction.
As the digital euro will be issued by the ECB and European Union (EU) state banks, Cipollone believes the digital currency will support the private sector to ensure “the singleness of money” is maintained across both public and private sectors.
“This convertibility ensures the singleness of money,” said Cipollone. “One euro has the same value as any other, throughout the euro area.
“Our objective is not therefore to replace private money or private innovation. It is to provide a stable public foundation to ensure day-to-day payments are cheap, resilient and inclusive. And to enable financial innovation to develop safely, at scale, in an integrated European market.”
Digital euro interest wiped
Addressing some of the financial sustainability challenges that comes with a new monetary instrument, Cipollone confirmed the digital euro will not be used as an investment vehicle, but as a means of payment.
He stated the digital currency will not be remunerated and individuals will be subject to holding limits; while bank limits are currently being considered to be between €500-€3,000.
A waterfall mechanism will be deployed to allow users to make transactions by linking their digital euro holdings to commercial bank accounts. This means users making payments with the digital euro that exceed their balance will still be settled as the difference will be made up by their bank.
A reverse-waterfall mechanism is also being considered, automatically transferring the bank account incoming transaction total sum above the holding limit or in other cases, lowering the threshold to the preference of the consumer.
“The digital euro is therefore not designed to disintermediate banks,” said Cipollone. “It is designed to safeguard their role as the monetary system becomes increasingly digital.”
“It is also worth noting that the discussion about the financial stability implications of the digital euro often disregards the fact that people can already easily and instantly transfer their deposits from bank accounts to other entities, where – unlike with the digital euro – they may be remunerated, unlimited or denominated in foreign currencies.”
Cipollone also estimates through ECB research that there will be a €127bn deposit inflow of digital euro deposits by 2034, exceeding the estimated outflows for business-as-usual scenarios for holding limits up to €3,000.
Pontes’ involvement
In September 2026, the ECB launched Pontes, a new tokenisation system to tokenised commercial bank deposits using distributed ledger technology (DLT).
Cipollone confirmed Pontes will be deployed to process and settle digital euro inter-bank transactions, acting as a settlement bridge between fiat and tokenised deposits.
Pontes will be able to test how regulated banks’ tokenised euro transactions can be exchanged on par with another bank’s tokenised deposit through the use of central bank-issued currency, acting as the underlying, risk-free settlement layer.
This is to address fears that tokenised and digital payments do not fracture the European ecosystem, as Cipollone warned “if tokenised finance develops on closed, incompatible platforms without a safe settlement asset, fragmentation could increase”.
“The question, therefore, is not whether payments and finance will become more digital. They already are,” said Cipollone.
“The question is how we can ensure that our monetary system continues to preserve the singleness of money, trust and stability, while also supporting efficiency, resilience and autonomy as this transformation unfolds.”