The wholesale digital euro unlocks access for banks to central bank money for tokenised markets, but questions remain about interoperability and market adoption.
The European Central Bank (ECB) has switched on its wholesale digital euro, meaning banks can settle tokenised transactions in central bank money.
The ECB’s Pontes platform opened for settlement on the morning of 22 September, bringing the wholesale digital euro into operational use for banks settling transactions recorded on distributed ledger technology (DLT).
An initial group of 13 banks has been onboarded, including Deutsche Bank, Santander and Société Générale, as well as four DLT operators including Clearstream and Axiology. The Deutsche Bundesbank has also joined as a market participant.
Banks can use the wholesale digital euro to settle tokenised assets, with the cash leg supported by the Eurosystem instead of privately issued settlement assets such as stablecoins.
However, the wholesale digital euro shouldn’t be confused with the retail digital euro being developed for consumers, which the ECB expects to pilot in 2027 before a potential launch in 2029.
The ECB has been working on both parts of its digital money strategy, but the wholesale system can operate under the existing framework, whereas the retail digital euro is subject to the EU legislative process.
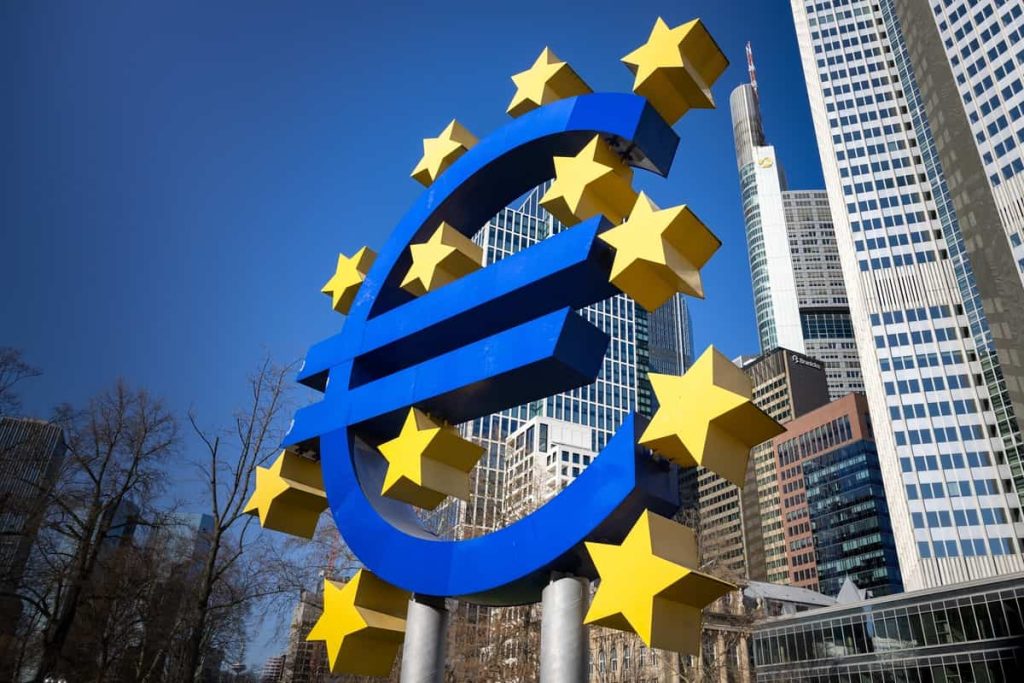
Why banks care about the wholesale digital euro
The main benefit for banks is the ability to settle tokenised financial assets using central bank money, which the ECB describes as a risk-free settlement asset.
Tokenisation can allow financial assets to be issued, traded and settled using DLT, but those transactions require a trusted form of money to complete the payment.
The Eurosystem’s 2024 tests found that access to a risk-free settlement asset was important for the adoption of DLT, leading to the development of Pontes as a bridge between DLT platforms and existing central bank infrastructure.
It is believed that this could provide a better link between tokenised markets and existing financial infrastructure, as well as reduce the need to introduce private settlement assets into the transaction.
ECB officials have warned that if European tokenised finance becomes dependent on dollar-denominated stablecoins, the role of the euro could be weakened and Europe could become reliant on financial infrastructure outside the region. The ECB has said that dollar-denominated stablecoins currently account for 99% of the global stablecoin market.
The ECB says the digital euro can provide a common euro-denominated anchor for tokenised markets and at the same time private forms of digital money such as stablecoins and tokenised deposits can continue to be used.
Pontes connects banks to Europe’s tokenised infrastructure
The launch of Pontes connects banks with financial markets, providing institutions with a way to settle tokenised securities in central bank money.
Speaking to Payment Expert earlier this week, Marius Jurglias, CEO of Axiology, said the system removes one of the barriers to adoption of tokenised securities by connecting DLT infrastructure with central bank money.
“Pontes is a major step towards bringing tokenised securities into mainstream capital markets,” said Jurglias.
“Institutions no longer have to choose between using new DLT infrastructure and settling in central bank money. Connecting the two gives tokenised securities the trusted cash leg they need to scale.”
However, Jurglias said the launch of the infrastructure is only part of the process, with Europe needing greater issuance, investment and liquidity in tokenised markets.
The ECB plans to expand Pontes over time, with enhanced features and longer operating hours expected before full implementation in 2028.
The central bank is also preparing to use the system, investing a small portion of its funds in tokenised securities. The ECB said the move will allow it to gain practical experience as an investor and build expertise in using DLT in financial markets.