

The payments infrastructure could be on the verge of a great transformation if it manages to implement AI beyond only fraud and risk scoring. With the capabilities of the newest technology, user experience may improve substantially, but only if it’s implemented right.
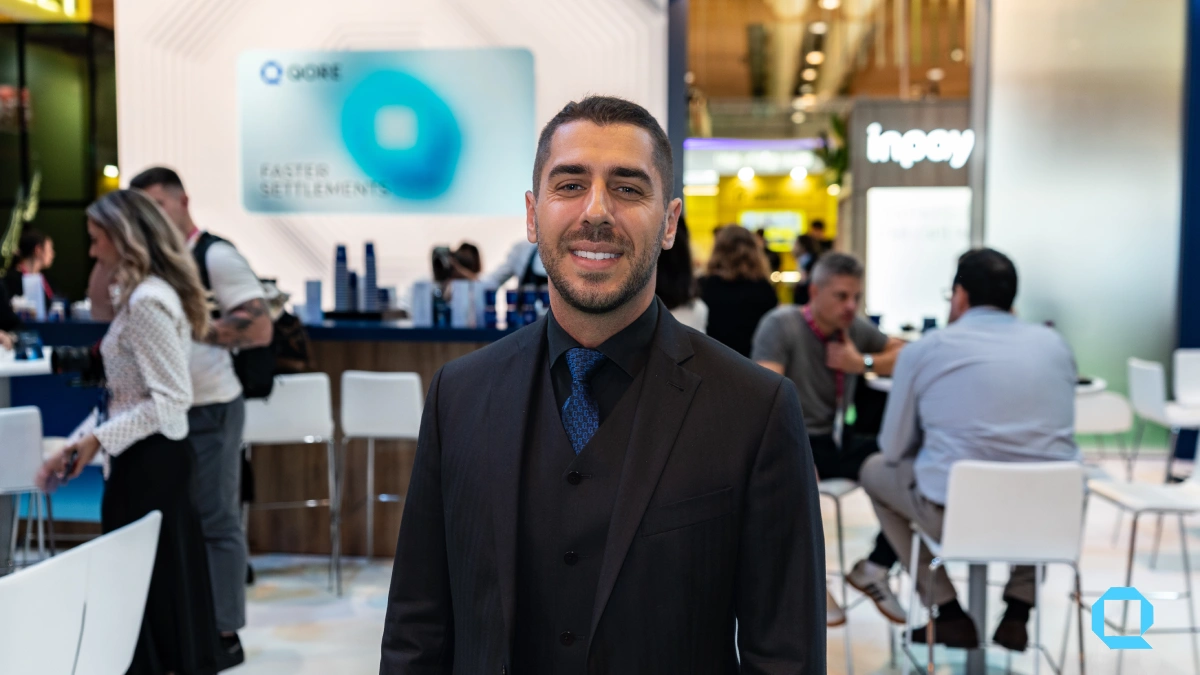
QORE Head of Business Development Vasos Varnava, tells Payment Expert how the bigger potential lies in applying AI to the parts of the payment journey that can directly improve performance, from identifying emerging issues to helping more transactions succeed.
How to win good transactions with AI
While there’s room for growth and wider application, AI’s strength currently relates to the assessment of transactions against behavioural and device signals before approval or decline. And, for Vasos, AI has the strongest foundation there because the data is clean, transaction volumes are high and the feedback loop is fast and measurable.
“The honest read is that AI in payments today is doing more defensive work, like catching bad transactions, than offensive work, or winning more good ones,” he says.
He explains that closing that gap represents the next major investment opportunity, particularly for transaction-heavy industries such as gaming, where revenue can be lost through payment failures that are not necessarily caused by a genuine inability to pay.
Bringing intelligence earlier
AI can help operators determine which payment methods to present to individual players. For Vasos, that is a natural extension of dynamic routing.
While routing currently determines which acquiring path has the best chance of approval for a transaction, similar intelligence could be applied before the player makes a payment-method choice. The potential commercial benefit is reducing drop-off caused by players selecting methods that are unlikely to succeed for their particular card, market or device.
Still, personalisation needs to be approached carefully. Hiding a payment method that a player actually wanted could create additional friction, meaning QORE would want to test the approach before positioning it as a live capability.
Behind the scenes, Varnava sees another significant opportunity in the exception queue: “The biggest impact is in the exception queue, not the main pipeline,” he says.
Rather than replacing already automated settlement processes, AI could pre-diagnose reconciliation problems, clusters of declines or payment-related support queries, giving employees a likely explanation before they begin investigating.
Making payment data predictive
Another of the most immediate applications for AI could be identifying unusual patterns before they become larger performance problems. QORE already brings settlement and approval data across markets, payment methods and acquiring paths into a single reporting layer, creating a consolidated dataset that AI could use to detect changes that might be difficult to spot through manual monitoring.
A possible case would be one with an approval rate that could begin slipping in one market, while a particular card range starts declining more frequently through a specific acquirer. A payment method could also begin performing below its historical baseline.
“These are the kinds of early signals that are easy to miss when a person is scanning dashboards manually across dozens of combinations, but that a model watching the same data continuously would catch in hours rather than weeks,” Vasos says.
The next step could be moving reporting beyond simply showing what happened towards explaining why it happened and what should happen next.
“The next layer is explanatory: not just ‘this batch of transactions declined,’ but why, grouped by pattern, that can be determined by a specific issuer, market, or method, with a recommended next step,” he says.
Data quality will determine AI’s value
The biggest obstacle to achieving these applications may yet have little to do with AI itself.
Payments data is generated across PSPs and acquirers that use different decline taxonomies, definitions and reporting cadences. For Vasos, that inconsistent data produces inconsistent AI output regardless of how sophisticated the underlying model is.
Regulation adds another challenge, particularly where automated decisions need to be explainable as well as accurate: “Operators aren’t reluctant to trust AI in the abstract, they’re reluctant to trust a decision they can’t audit, built on data they don’t fully believe in,” he says.
For payments providers, therefore, the AI opportunity ultimately starts with the foundations. Fix the data and the explainability, and trust problems shrink considerably.