Declined deposits do not always mean a player’s payment method cannot be used. Many times, transactions fail because of how they were routed, the data attached to them or the acquiring path they took.
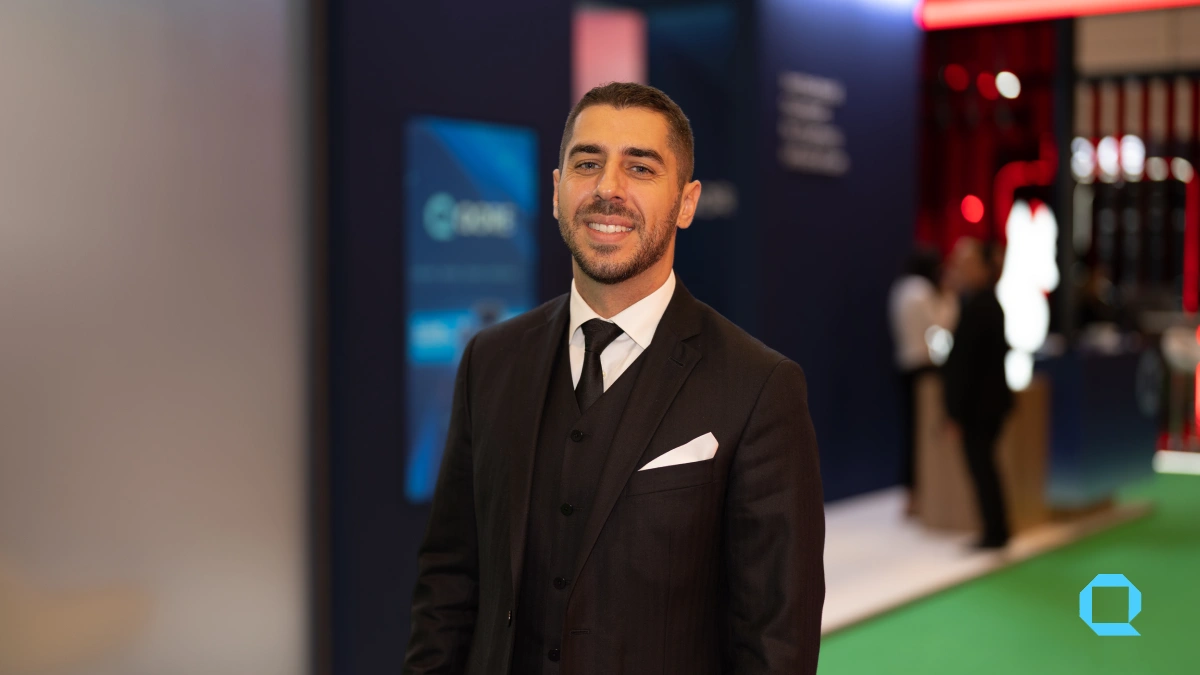
Vasos Varnava , Head of Business Development at QORE, tells iGaming Expert how this distinction is central to understanding how much room payment optimisation has to recover lost deposit volume.
Not every decline is a lost transaction
Many factors may interfere with payment declines in a player’s journey. Vasos explains that there are two broad categories for failed transactions, shaped by multiple conditioning factors.
On one end, hard declines, such as insufficient funds, closed accounts or genuine fraud flags, are unlikely to be recovered through optimisation.
On the other hand, soft declines can result from factors including issuer risk scoring, unfamiliar merchant data, mismatched currency or BIN routing, outdated card information and transaction timeouts.
“In our experience the soft-decline bucket is the majority of ‘lost’ transactions,” says Varnava. “That’s the part optimisation actually moves. We see it in how much recovery happens purely from re-routing the same transaction through a better-matched acquiring path.”
The opportunity is not to override genuine issuer rejections, but to recover transactions that failed because of how they were processed. By identifying where routing, data or payment configuration contributed to the decline, operators can give otherwise viable transactions another chance to succeed.
Optimisation happens across multiple layers
QORE reports average approval ratios of more than 85%, with Vasos attributing that performance to a combination of factors rather than a single optimisation tool: “The process itself isn’t one lever, it’s the compounding of several,” he says.
Intelligent routing can direct each transaction towards the acquiring path most likely to clear it, while direct acquiring relationships can remove additional hops and potential failure points. To avoid unnecessary friction in the payment flow, adopting local currencies and other local payment methods represent another opportunity, particularly in markets where cards are not the dominant payment instrument.
For Vasos , there is further room to improve by moving away from static routing rules towards decisions made at the individual transaction level. He explains that smarter routing still “has more room to run,” as operators have yet room to route dynamically at the individual-transaction level, instead of routing by static rule sets, like they are now.
AI also makes part of QORE’s approach to the payment solution, as pattern data across markets, issuers and payment methods inform routing decisions closer to real time rather than just relying on rules that are updated periodically.
More providers don’t help optimisation
Many operators may opt for adding more PSPs and acquiring partners to create more opportunities to find a successful payment route. However, the reality is that fragmentation can ultimately lead to harder optimisation.
“More providers on their own don’t buy you a higher approval rate. They buy you more places for a transaction to fail differently, and less visibility into why,” Vasos explains.
Each provider can use different reporting formats, decline codes and definitions of what constitutes a decline. The result? “The opposite of optimisation,” he says, as operators working with several providers may struggle to build a consistent picture of where transactions are failing.
“You can’t fix what you can’t see consistently,” he adds.
Better reporting can be just as important as better routing. Without consistent decline reasons, operators may attribute lost deposits to churn or player behaviour when the underlying issue was a fixable routing or data problem.
Profitable conversion beats maximum approvals
Approval rates are important, but there is also a limit to how far operators should pursue them without looking into other sides of the process. “Approval rate in isolation is a vanity metric,” explains Vasos. Increasing the rate by weakening fraud controls, for example, can simply replace one cost with another, as chargeback exposure may grow in return.
The objective, he argues, should instead be maximum approvals within acceptable fraud and processing-cost thresholds. A transaction that succeeds but subsequently results in a chargeback or fraud loss does not represent a genuine improvement.
That balance becomes increasingly important in mature iGaming markets, where operators are competing for many of the same players. That’s why operators gain a structural edge when they manage to convert more of the deposits they are already attempting, while also not overspending on acquisition.
For operators, the opportunity in transaction optimisation therefore lies not in overturning every decline, but in identifying the recoverable transactions hidden within them. As routing becomes more dynamic and payment data more actionable, even incremental improvements in approval can translate into meaningful additional volume of deposits.