The Bank of England has indicated that there is no rush to issue a digital pound. Here, we explore what a CBDC is and how it differs from stablecoins.
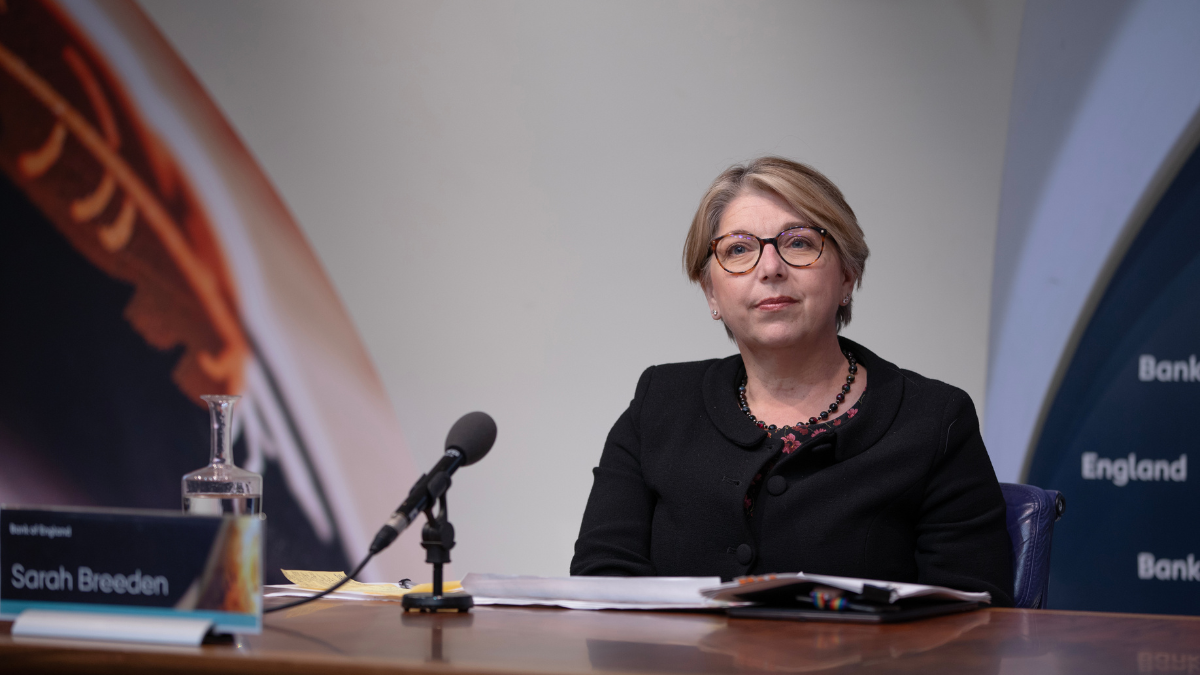
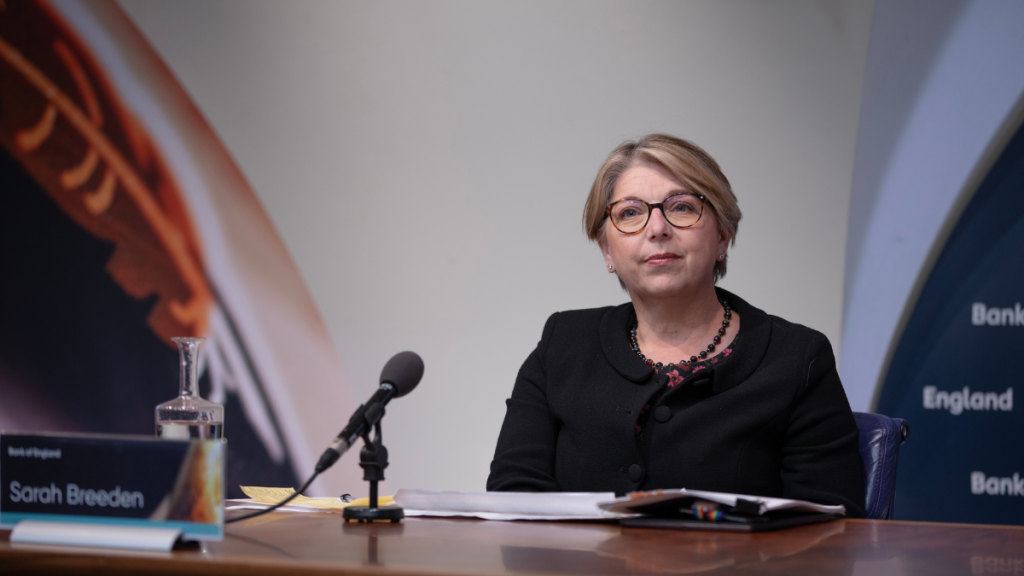
This week, Sarah Breeden, Deputy Governor for Financial Stability at the Bank of England, said the UK may not need a digital pound for retail users “that quickly”.
Her argument was sterling stablecoins issued by regulated firms and tokenised deposits issued by commercial banks could deliver the same benefits as a digital pound, a type of CBDC, or central bank digital currency.
But what is a CBDC, and why have central banks like the Bank of England been exploring them?
What is a CBDC?
A CBDC is a digital form of a national currency, issued by a central bank. It represents a direct liability of the central bank – much like a physical banknote – rather than a claim against a commercial bank.
Most of the money in circulation across the globe is not central bank money. Balances in a current account are, in effect, a claim against the bank where the funds are held.
Ricardo Correia, Partner at Bain & Co, previously explained the role of CBDCs to Payment Expert: “A CBDC represents the digital equivalent of a physical £10 note in your wallet and can be depicted as a token on your mobile device.
“On the other hand, digital fiat currency is akin to your Barclays bank account, which you access on your mobile or the internet through your banking app.”
A CBDC also differs from crypto-assets; coins such as Bitcoin, for instance, have no issuer and operate on a decentralised network. Stablecoins are issued by private entities, pegged to an existing currency (such as the US dollar), and backed by reserves held by the issuer.
A CBDC, by contrast, is issued by the state. Delia Pedersoli, now an independent consultant, previously told Payment Expert CBDCs “don’t need to be decentralised and have been developed to easily scale to the volumes needed for day-to-day retail payments.”
Retail CBDCs would be held and used by households and businesses. Wholesale CBDCs are used exclusively for the settlement of transactions between financial institutions. The digital pound currently under consideration in the United Kingdom is a retail CBDC.
Why central banks are exploring them
The Atlantic Council cites several common motivations: financial inclusion for the unbanked, competition and resilience within domestic payment systems, lower transaction costs, programmable money, and the faster implementation of monetary and fiscal policy.
According to Correia, Facebook’s 2019 announcement regarding its currency, Libra – later renamed Diem – prompted many central banks to take action. “This event served as a wake-up call for governments and banks,” says Correia.
Pedersoli also noted a digital pound could reduce the costs of international transfers. “Operating on payment rails with less complexity allows digital currencies to provide instant refunds for things like missed deliveries,” she said.
However, the Atlantic Council has pointed to certain risks. Households might move their bank deposits into a CBDC, which would limit the lending capacity of banks. CBDCs could become targets for cyberattacks and would require regulations concerning privacy, consumer protection, and anti-money laundering efforts.
In the US, Republicans have opposed a digital dollar due to privacy concerns. “By including our ‘Anti-CBDC Surveillance State Act’ in the NDAA, we ensure that unelected bureaucrats can NEVER trade away the financial privacy of Americans for a Chinese Communist Party-style surveillance tool,” said Tom Emmer, Majority Whip in the U.S. House of Representatives, in July 2025.
The Bank of England has said neither it nor the government would be able to program digital pounds or dictate how they are spent, reflective of the sentiment in a UK House of Commons Treasury Committee report titled: “The digital pound: a solution in search of a problem?”
This week, Breeden indicated the Bank of England wants UK companies to develop successful stablecoins pegged to the British pound.
“I do not want citizens and businesses in the United Kingdom to have to look elsewhere for access to innovative payment technologies”, she said.
“Relying exclusively on dollar-denominated stablecoins would be madness.”
The global status of CBDCs
The Atlantic Council’s CBDC tracker, last updated in May 2026, identifies 146 countries and currency unions that are exploring adoption. These jurisdictions represent more than 98% of global GDP; in May 2022, that figure stood at 87.
Three countries have now fully launched a CBDC: the Bahamas, Jamaica, and Nigeria. The tracker also records 41 pilot projects. Every G20 member, with the exception of the United States, is exploring the possibilities for adoption.
China’s e-CNY is the largest pilot project. According to the Atlantic Council, more than 3.4 billion transactions had been processed using the e-CNY for consumer use by December 2025, with a total value of approximately 16.7trn renminbi ($2.3trn).
Canada, Australia, and Norway have assigned a lower priority to CBDCs for consumer use, according to the Atlantic Council.
Central banks are currently focusing primarily on projects for wholesale transactions, such as the European Central Bank’s (ECB) ‘Project Pontes,’ the issuance of a wholesale CBDC in Singapore, and the ‘Drex’ pilot project in Brazil. The ECB is also conducting a pilot for a digital euro.