Correspondent banking moves money across borders through chains of intermediary banks. Here is how the system works, and where it is under strain.
Correspondent banking lets a bank offer customers payments in countries and currencies where it holds no branch or licence. One bank, the correspondent, holds deposits for another, the respondent, and moves money on its behalf.
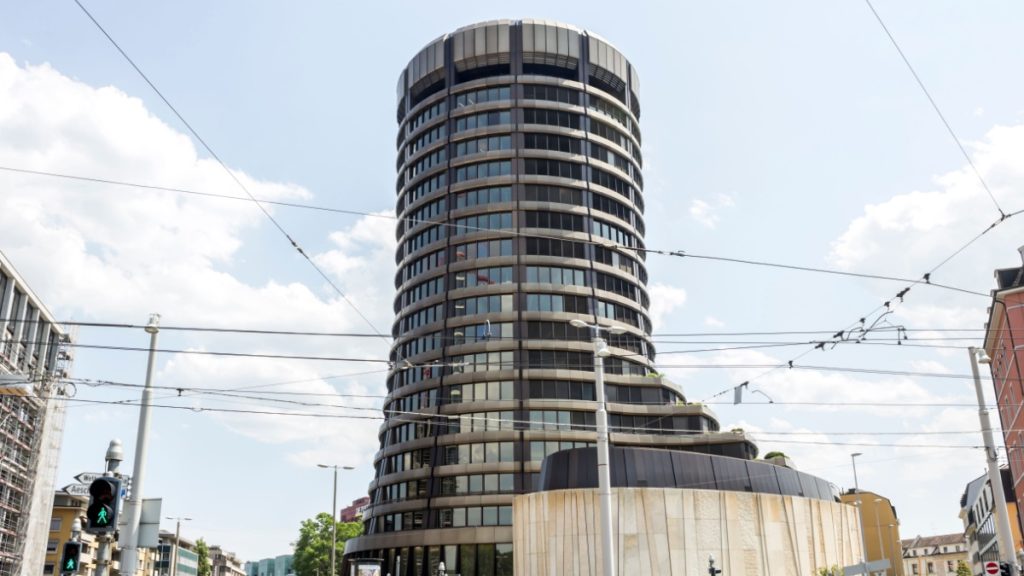
The Bank for International Settlements calls the arrangement critical infrastructure for cross-border payments. Remittances, trade finance and humanitarian transfers rely on it too.
To give a sense of its importance, cross-border payment flows were worth almost $150tn in 2017 and are projected to exceed $250tn by 2027, according to the Bank of England, and correspondent banking carries a large share of this value.
Correspondent Banking: How the chain moves money
A respondent bank holds an account with its correspondent to settle payments abroad. The respondent calls this a nostro account, meaning “our account with you”; the correspondent records the same balance as a vostro account, “your account with us”.
A customer sending an international transfer prompts the respondent to send a payment instruction over SWIFT, the messaging network connecting more than 11,500 institutions across 200 countries and territories, and the correspondent then executes the payment through local clearing rails.
Correspondents require respondents to keep the nostro account funded, tying up liquidity the respondent cannot deploy elsewhere.
A single correspondent rarely covers every route. When no direct relationship links the sending and receiving banks, the payment passes through a chain of intermediaries, each holding an account with the next, until it reaches the destination bank.
Those chains are the main reason international transfers have historically settled more slowly than domestic ones, according to J.P. Morgan. Each hop adds a fee, a foreign-exchange margin and a point where the payment can stall, and the sender often cannot see the full cost or the arrival time in advance.
Why the network is shrinking
Banks have cut correspondent relationships since the 2008 financial crisis, a trend the industry calls de-risking.
Compliance costs for anti-money-laundering checks and sanctions screening rose, and many correspondents judged smaller respondent banks in higher-risk markets no longer worth the exposure. The BIS documented banks reducing the relationships they maintain while opening few new ones.
The effect concentrates traffic, resulting in fewer correspondents handling more of the volume, which lengthens some chains and raises costs on the corridors which lose their direct links.
However, research from the Centre for Economic Policy Research (CEPR) and European Bank for Reconstruction and Development (EBRD) found when respondent banks lost correspondent relationships, corporate borrowers in those markets exported less, with small and medium-sized enterprises hit hardest; some firms stopped trading altogether.
The G20 launched a roadmap in 2020 to make cross-border payments faster, cheaper and more transparent, with most targets set for the end of 2027. In 2025, a progress report by the Financial Stability Board concluded improvements had not yet reached end-users and that the 2027 targets were unlikely to be met on schedule.
Where the model is heading
Alternatives now compete with the correspondent chain on specific routes. Blockchain rails and stablecoins settle some transfers directly between participants, removing intermediaries. China’s CIPS and India’s UPI linkages route payments outside dollar correspondent networks, while card networks are building their own cross-border infrastructure.
Kellie Johnson, SVP Payments Americas at RedCompass Labs, told Payment Expert in April a question remains over who fills the intermediary role.
“A key question will be who fills that intermediary role – whether it is traditional correspondent banks or major card network players like Visa and Mastercard that are actively building out their cross-border infrastructure,”she said. “That competition could significantly reshape the future of correspondent banking.”
Tokenised bank deposits offer another route. The BIS-led Project Agorá is testing whether tokenised central bank reserves and commercial bank deposits can settle wholesale cross-border payments on shared infrastructure.
Sabih Behzad, Head of Digital Assets and Currencies Transformation at Deutsche Bank, said: “In a landscape with fragmented infrastructure, the role of correspondent banks will be significantly rewired.”
Correspondent banking still carries most cross-border payment value, and remains the default for the currencies and corridors alternatives do not yet cover.